Why do some audits move quickly while others turn into weeks of emails and missing files? Often, the difference is the PBC file. A finance team that closes balances, prepares reconciliations and keeps evidence in order gives the auditor something workable from day one.
In the UAE, tax records and corporate documents may also feed into the audit. Jitendra Chartered Accountants (JCA) works with UAE businesses on external audits, accounting and related tax matters.
What Is an Audit PBC List in the UAE?
PBC means “Prepared by Client.” It is the list of schedules, documents and explanations the auditor asks the company to provide before or during fieldwork.
There is no single UAE PBC checklist for every business. A trading company with inventory will receive different requests from a professional services firm. The list also changes with company size, reporting framework, audit scope and issues found in the prior year.
Start With the Trial Balance, Not the Document Folder
Invoices help only after the numbers being audited are settled. The year-end trial balance should agree with the general ledger and draft financial statements.
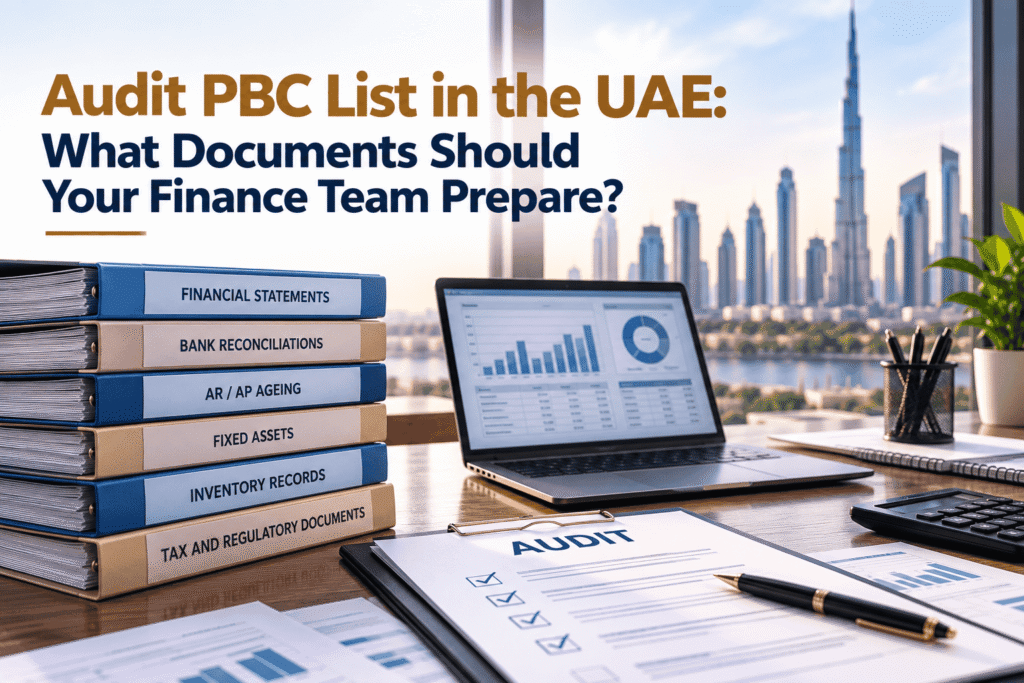
A practical first pack normally includes:
- Final trial balance and general ledger
- Bank statements and bank reconciliations
- Accounts receivable and payable ageing
- Fixed asset register and depreciation schedule
- Inventory summary, where applicable
- Loan, related-party and shareholder balance schedules
- Major journal entries with supporting explanations
- Prior-year audited financial statements
- Status of prior-year audit adjustments and management letter points
- Bank, customer and supplier contact details and authorisation letters for audit confirmations
- Post-year-end bank statements and payment records
Old reconciling items deserve attention early. A bank difference carried for months usually creates more work than a fresh timing difference with clear evidence.
Revenue, Receivables and Bank Evidence Need to Agree
Revenue testing may move from the sales ledger to invoices, customer contracts, delivery evidence and bank receipts. Credit notes issued after year-end can also become relevant.
Receivables need the same traceability. Ageing reports should agree with the ledger, while long-outstanding balances may need collection evidence, impairment support or management explanation.
Auditors may also request confirmation of balances directly from banks, customers and suppliers. Finance teams should have the relevant contact details and signed authorisation letters ready to avoid delays.
Expenses, Payroll and Payables Should Have an Audit Trail
Large or unusual expenses may receive closer testing. Keep supplier invoices, contracts and approval evidence accessible. Payroll requests can include payroll summaries, employee records, gratuity calculations and evidence that payroll totals reconcile to the ledger.
Payables ageing needs cleaning too. Debit balances, old supplier credits and balances with no recent movement should be understood before fieldwork begins.
Auditors may also examine post-year-end bank statements and payments to identify liabilities that existed at year-end but were not recorded. Keeping these records available helps the finance team respond to such queries without searching through later transactions.
Fixed Assets, Inventory, Loans and Leases
A fixed asset register should show opening cost, additions, disposals, depreciation and closing balances. New purchases need invoices and ownership evidence.
For inventory, quantity records, valuation workings and count sheets may be requested where stock is material. The auditor’s attendance at the year-end stock count should be arranged before year-end, allowing sufficient time to plan the observation and related audit procedures.
Loan agreements, repayment schedules, interest calculations and lease contracts should also be ready rather than rebuilt after testing starts.
UAE Tax and Corporate Records Auditors May Ask For
VAT returns, Corporate Tax filings, tax reconciliations and supporting calculations can affect financial statement balances. The PBC file should also include the Corporate Tax computation, current tax provision and deferred tax provision, where applicable.
Under Ministerial Decision No. 84 of 2025, taxable persons outside Tax Groups with revenue exceeding AED 50 million during the relevant tax period, as well as Qualifying Free Zone Persons, must prepare and maintain audited financial statements for Corporate Tax purposes.
For Corporate Tax, the FTA says relevant records and documents should be retained for at least seven years after the tax period ends.
Many UAE free zones also require audited financial statements for annual compliance or licence renewal. For example, JAFZA requires Free Zone Establishments (FZEs) and Free Zone Companies (FZCOs) to submit an updated audit report annually.
Trade licences, constitutional documents, shareholder information, board minutes, related-party details and material contracts may also be requested when they affect the accounts.
How to Keep the PBC Process Under Control
Use one tracker instead of scattered email threads. Give each request an owner, due date and status. Mark whether the auditor accepted the file or asked for more evidence.
File names should explain what is inside. “Bank reconciliation Dec 2026” is more useful than “scan0047.pdf.” Schedule totals should tie back to the ledger before submission.
Review the prior-year management letter as well. If an audit adjustment or control weakness remains unresolved, prepare an explanation and any supporting records before the auditor raises the issue again.
How Jitendra Chartered Accountants Can Help
At Jitendra Chartered Accountants, we provide external auditing services for UAE businesses, including statutory and financial statement audits.
Is your finance team still building the PBC file after the audit has started? We can review the accounting position, carry out the audit within the agreed scope and support tax-related records that affect the financial statements. Contact JCA to discuss your UAE audit requirements.
FAQs
What documents are usually included in an audit PBC list in the UAE?
Usually, your finance team prepares accounting records, reconciliations, schedules, contracts, tax documents, confirmation details and other supporting evidence requested by the auditor.
Is the same PBC list used for every UAE company?
No. A PBC list should reflect audit scope, company activity, reporting framework, material balances, identified risks and planned auditor testing procedures.
What causes delays during a UAE financial audit?
Missing reconciliations, unexplained balances, incomplete invoices, old receivables, unsupported journals and inconsistent schedules often create extra audit questions and follow-ups.
When should the finance team start preparing the PBC file?
Start before fieldwork and arrange any required year-end stock count attendance in advance. Assign an owner to each request so documents can be supplied without disrupting routine finance operations.
Can auditors ask for VAT and Corporate Tax records?
Yes. Tax filings, Corporate Tax computations and tax provisions may be requested when they affect financial statement balances, revenue, expenses or compliance disclosures during the audit.